How to Build a Rainy Day Fund That Covers Real Surprises
A rainy day fund is cash reserved for an expense you did not plan for: a car repair, a medical bill, or a broken appliance. Your starting amount should reflect your circumstances, the kinds of surprises you have faced before, and what it would take to keep essentials covered if another one happened.

A rainy day fund is cash reserved for an expense you did not plan for: a car repair, a medical bill, or a broken appliance. Your starting amount should reflect your circumstances, the kinds of surprises you have faced before, and what it would take to keep essentials covered if another one happened.
The numbers behind the story
How many adults could cover a $400 surprise without carrying debt?
In 2025, 63% said they would use cash, savings, or a credit card paid in full at the next statement. That is above 2013's 50%, but below the 2021 peak of 68%. This measures a hypothetical payment choice, not the amount actually held in savings.
Read the chart as a table
| Category | Adults using cash or its equivalent |
|---|---|
| 2013 | 50% |
| 2014 | 53% |
| 2015 | 54% |
| 2016 | 56% |
| 2017 | 59% |
| 2018 | 61% |
| 2019 | 63% |
| 2020 | 64% |
| 2021 | 68% |
| 2022 | 63% |
| 2023 | 63% |
| 2024 | 63% |
| 2025 | 63% |
Source or method: Federal Reserve, 2025 SHED, figure 24 · As of . Illustrative calculations are identified in the chart description.
Try it with your numbers
Build your rainy-day fund plan
Start with a bill you would struggle to cover. Then see how a bigger cash reserve could handle an income gap. Your first target is a milestone, not a rule.
Step 1 · Cover a likely surprise
$640
Your first cash milestone
27% of your first milestone saved
Still to save
$465
At this pace
5 months
Step 2 · Prepare for lost income
$7,200
Your total cash target for 3 months of essential costs; it includes the first milestone, so these targets are not added together.
$7,025 more from today · about 71 months at this pace
This is a planning estimate without interest or future withdrawals. Income stability, dependents, and insurance deductibles can change your target.
Free to use. Sign in only if you choose to save.
For context, in 2025, 63% of adults said they would cover a hypothetical $400 expense entirely with cash, savings, or a credit card paid off at the next statement. Separately, 55% said they had set aside money for three months of expenses in an emergency or rainy day fund, according to the Board of Governors of the Federal Reserve System. Both shares were unchanged from 2024, and the three-month share was down from 59% in 2021. The first figure describes how people say they would pay a bill. The second describes savings they report holding.
Here is the plan in short. Save for one likely bill first, then work toward a set number of months of essential costs. Keep that cash in an insured account you can access quickly enough for the bills it must cover. Automate a transfer sized to what each paycheck can spare, and spend ten minutes each month checking the balance against your current bills. The sections below walk through each step with worked examples.
Choose your first rainy day fund target
Look back at the last year or two. What was the largest unplanned bill you would have struggled to pay without borrowing? Use that amount as a first milestone. If you cannot save it all at once, choose a smaller target you can reach, then raise it. A $300 buffer that exists is more useful than a $3,000 goal that never gets started.
Illustrative scenario: Maya has $175 set aside when her car needs a $640 repair to get to work. She can use the $175, but must find another $465. If she puts that remainder on a card and carries a balance, interest makes the surprise more expensive. The small fund still mattered: it reduced what she had to borrow and made the bill less disruptive.
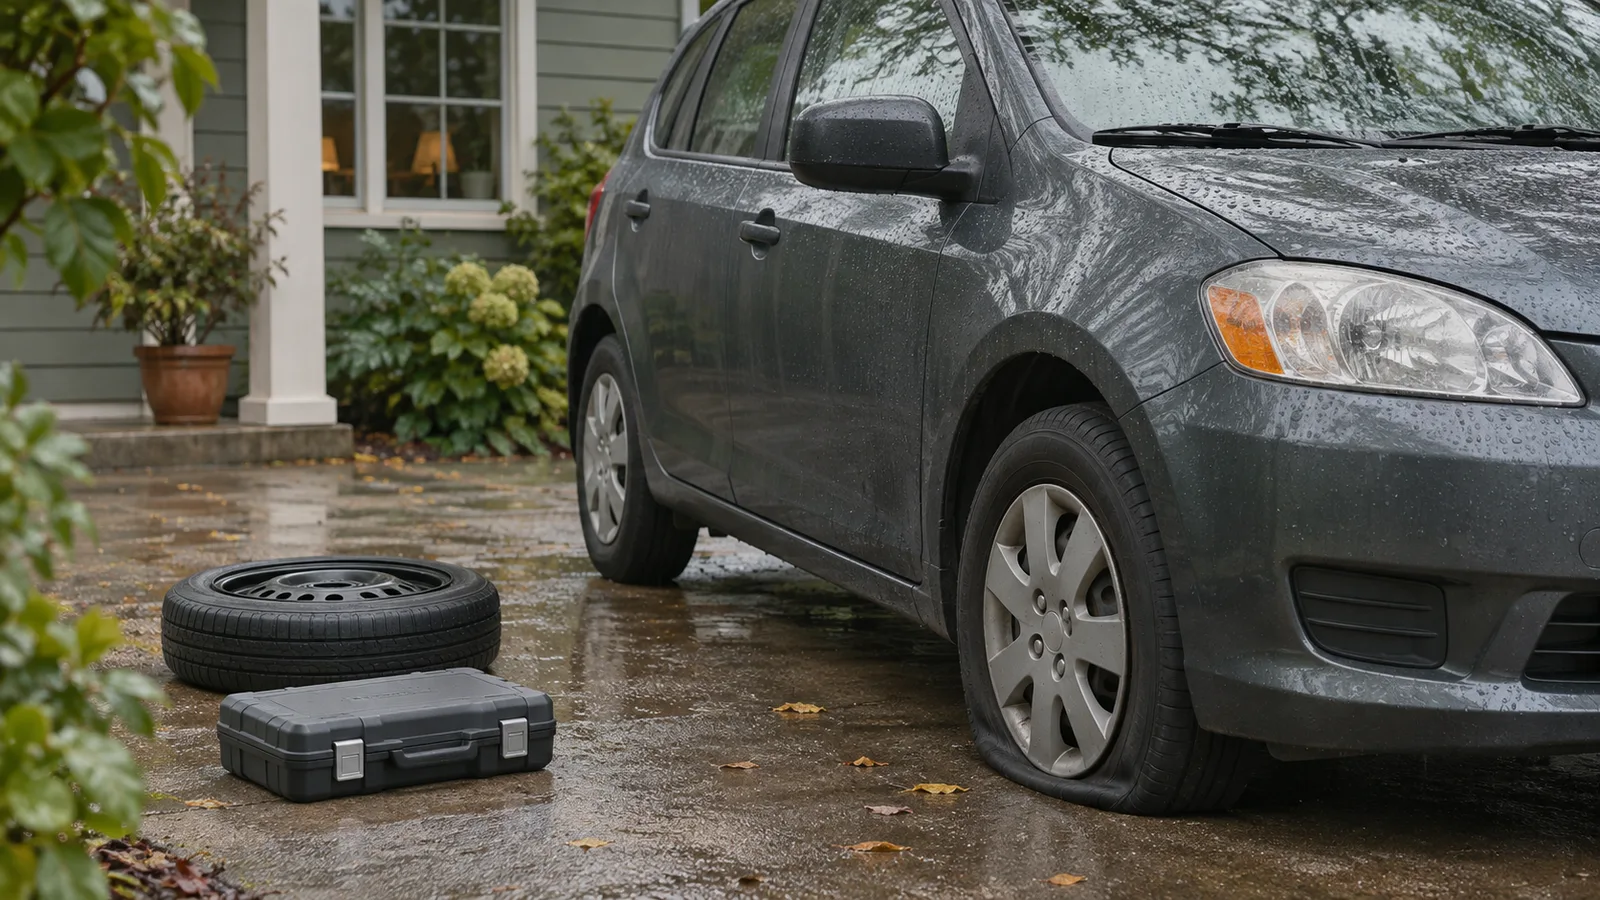
After the repair, Maya sets a first rebuilding milestone of $300 and a full repair-sized target of $640. Starting from zero and moving $25 a week, she could reach $300 in 12 weeks and $640 in 26 weeks, before interest and assuming no further withdrawals. If $25 risks an overdraft, she lowers the transfer and lengthens the timeline. The method is what carries over: choose a plausible bill, protect rent and other essentials, then make the first milestone reachable. To test your own numbers, write down the bill you expect, your current balance, and a weekly amount you can spare. Subtract the balance from the bill, then divide the gap by the weekly amount to see how many weeks the milestone will take.
Then plan for lost income
A one-time bill and a gap in income are different problems. Add up essential monthly costs: housing, utilities, groceries, transportation, insurance, minimum debt payments, and other obligations you cannot pause. Multiply that amount by the number of months you want to cover. For example, assume essentials total $2,400: one month is $2,400 and three months is $7,200. The first layer covers a likely bill; the next layer addresses the different risk of missing income.
The Board of Governors of the Federal Reserve System survey cited at the top counts adults with three months of expenses set aside. Its $400 result measures a hypothetical payment choice, not the balance people held in savings. Treat the three-month measure as a reference point for your longer rainy day fund target, not a rule. With the assumed $2,400 in essentials, three months is $7,200. If a partner's paycheck would keep covering $1,000 of those costs, the gap your cash must fill drops to $1,400 a month, or $4,200 for three months. Adjust the months of coverage for your income stability and available support.
Income volatility, dependents, health costs, job security, and access to other support can change the target. Write down your available cash, essential monthly spending, and the months you want to cover. These inputs let you check an estimate from the cash runway tool against your own bills. Multiply essential monthly spending by the months you want to cover to calculate a target. Divide available cash by essential monthly spending to estimate how long it would last. Keep money reserved for predictable bills out of the available-cash figure.
Illustrative scenario, continued: Once Maya's $640 repair layer is in place, assume her essential costs come to $1,800 a month, based on her actual bills rather than a percentage of salary. Her next milestone is one month of essentials, so she needs another $1,160. At $25 a week that takes about 47 weeks. If a pay rise let her move $40 a week instead, it would take 29 weeks. If her hours become unpredictable or her household depends on her paycheck alone, she would then aim for more months. Revisit this layer when your household costs or income stability change.
If high-interest debt competes with saving, try this tie-breaker: would an extra debt payment leave you unable to cover the next plausible urgent bill without borrowing again? If so, keep enough accessible cash for that bill while maintaining minimum debt payments. Once that first layer is covered, compare the debt's interest rate with what your savings earns. If the debt costs more, consider directing the next surplus toward it before extending the cash target. A likely income gap can change that choice: write down the essential payments that would come due during the gap before committing cash to debt repayment.
Try a stress test before increasing the target: if income stopped for four weeks, which payments would still be due, and when? Rent and utilities may not wait for an investment to settle. If a partner's income or other support would continue, note that too. Your answer may be different from the number on a generic checklist.
Keep it available when you need it
Emergency cash should be easy to reach without selling an investment at an unfavorable price. A separate savings account can keep the balance visible without mixing it with routine spending. For your first layer, compare access, fees, and insurance before the advertised rate.
Before opening an account, make one access checklist: which account would pay an urgent bill, how would money reach it, when would it become available, and what minimum balances, transfer fees, or limits apply? Check the account terms. If you already hold the account, try a small transfer and record when it becomes spendable. Use the result to decide how much needs to remain in checking for a bill due today. Keep the checklist with your account details. A slightly higher yield may not compensate for a delay when you need cash.
Before relying on deposit protection, collect your account names, balances, institutions, and ownership details from your records. Include savings held for annual bills as well as your emergency cash. Use that list alongside deposit-insurance scenarios to prepare questions for the institution. Ask whether its deposits are insured by the FDIC (for banks) or the NCUA (for federally insured credit unions), and which ownership category each of your accounts falls under, such as single accounts, joint accounts, certain retirement accounts, or trust accounts. Coverage is counted separately by ownership category, so ask how it would apply to your actual accounts. If you are considering another account at the same bank, ask how your existing balance and proposed deposit would be considered together. Request the FDIC or NCUA coverage rules the explanation relies on, and flag any unclear answers for follow-up before moving funds.
Ask the institution: “Does this account qualify for deposit insurance, and how do my other accounts here affect its coverage?” Keep its explanation with your account records.
Should part of it go in a CD or Treasury bill?
Usually not for your first cash layer. Build an immediately accessible rainy day fund before considering a CD or Treasury bill for money you expect to leave until maturity. Read the terms and ask the provider how you could access the money earlier, what costs might apply, and how much you could receive. Keep a proposed deposit out of your immediate cash total until you have checked whether it could pay a bill on the day it is due. Choose a maturity that fits when you expect to need the money.
Illustrative scenario: Assume you have $4,000 saved, a $900 insurance premium due before a proposed CD matures, and a plausible $1,200 car repair to cover. Reserving the premium leaves $3,100 in emergency cash. Putting $2,000 of that in the CD leaves only $1,100 accessible for the repair, a $100 shortfall. Interest available later cannot close that gap on repair day. Keeping the premium and repair money available leaves at most $1,900 to consider putting in a CD, and less if this cash must also bridge missed income.
In this example, committing the full $1,900 leaves no margin above the assumed repair cost. If the repair estimate were $1,400 instead, the amount left to consider for a CD would fall to $1,700. Check the repair assumption before comparing yields: use an estimate for the work your car might need, rather than treating the example's amount as a standard. Before choosing an amount, list the bills due before maturity and subtract their reserves. Mark the remaining accessible balance in your savings plan, then compare it with your first emergency target. If it falls short, direct your next contribution toward closing that gap.
| When you may need it | Cash choice to examine | What to check first |
|---|---|---|
| Today or tomorrow | Checking or linked savings | Transfer speed, fees, and available balance |
| Within weeks, but not immediately | Insured savings or money market deposit account | Transfer timing and deposit insurance |
| Only after a separate immediate buffer exists | CD or Treasury bill with a suitable maturity | Early-access friction, penalties or sale-price risk |
Check whether a product called “money market” is a bank deposit account or a mutual fund. Read its coverage and risk information before assuming it has deposit protection. Ask the provider to identify the exact product and explain what could affect your balance. Match the product name in the agreement to the account you intend to open, especially if the provider offers both kinds.
For a CD, use the agreement to answer these questions: when does it mature, what are the withdrawal terms, and what instructions must you give if you do not want it renewed? Put any action deadline from the agreement in your calendar. For a Treasury bill, ask the provider what holding it to maturity or selling it earlier would involve, including timing, costs, and what could affect the proceeds. Compare the quoted yield after you understand those answers. Imagine the car repair arrives before maturity: write down which accessible balance would pay it. If that balance falls short, reduce the amount committed or build more cash first.
Make replenishment automatic
For regular pay, schedule a transfer after the deposit becomes available, or use a payroll split if your employer offers one. For irregular income, set a transfer ceiling from each payment after checking what must last until the next one. For example, assume a $900 payment arrives, $700 must cover essentials, and you need a $150 checking cushion. That leaves at most $50 for the rainy day fund. Write down the date the $700 must last through. If the next payment is uncertain, extend that spending window and recalculate before transferring; an unpaid invoice cannot cover today's spending.
In the same example, an additional $35 essential expense would reduce the transfer ceiling to $15. An additional $75 would use the entire apparent surplus and leave a $25 gap while preserving the checking cushion. Pause the transfer and decide how to cover that gap. After a withdrawal, redirect a discretionary savings contribution only after checking that the same bills and cushion remain covered. If no surplus remains, skip the transfer and reassess when the next payment arrives.
Review the target when rent, household size, insurance deductibles, or income changes. Before setting the next emergency-fund transfer, calculate what an approaching annual bill needs from each remaining paycheck. Suppose a $720 premium is due after six more paychecks and you already have $240 reserved. The remaining $480 requires $80 from each paycheck. Subtract that contribution from the money available for emergency saving; otherwise, the apparent surplus already has a job. If $80 will not fit, identify the gap now and check what payment arrangements are available before the bill comes due.
Decide what the fund is for before you need it
A sudden medical bill, an essential appliance failure, or the income gap after a job loss could qualify. Annual insurance premiums, holiday spending, and a known car registration renewal are predictable costs, even if the due date is uncomfortable. For a borderline expense, ask what changed: replacing tires you knew were worn is a planned cost; a sudden blowout that makes the car unsafe may justify using the fund. This is not a moral test. If an essential planned bill arrives before its reserve is ready, cover the need and record the shortfall. Then work backward from its next due date to set a contribution for each paycheck.

When a real emergency uses the fund, record what happened and how much you spent. If $480 of a $600 balance went to a repair, the next goal is to replace $480, not to punish yourself for using the money. Restart a manageable transfer, even if it is smaller than before. The balance is supposed to move when life happens.
A ten-minute check-in you can repeat
Once a month, check the available balance, pending reimbursements, reversed transfers, and changed bills. Open your account transactions and latest bills side by side. Match cleared withdrawals to their receipts so the same repair does not get counted twice. Compare your current rent and insurance deductible with the amounts in your written plan before choosing the next transfer.

Sources note: The 63% payment-choice and 55% rainy day fund figures above are self-reported adult responses in “Emergency Savings and Unexpected Expenses,” within the “Savings and Investments” section of the Report on the Economic Well-Being of U.S. Households in 2025, published by the Board of Governors of the Federal Reserve System. Both measures were unchanged from 2024. Figure 24 in the report's PDF tracks how adults said they would pay a hypothetical $400 expense, rather than savings balances: 50% in 2013, 53% in 2014, 54% in 2015, 56% in 2016, 59% in 2017, 61% in 2018, 63% in 2019, 64% in 2020, 68% in 2021, and 63% in each year from 2022 through 2025. The article's savings scenarios use hypothetical amounts.
The same cash balance supports both needs, so the first and longer targets are milestones, not amounts to add together. Using the earlier assumption of $2,400 in monthly essentials, a $7,200 balance covers three months before any emergency withdrawal. If an urgent bill uses some of that money, subtract the payment and calculate the remaining coverage again. Record the lower balance in your plan so a repair payment does not leave you relying on an outdated estimate.
For example, suppose an insurer has approved reimbursement for a repair but the payment has not arrived. Keep the claim reference and expected payment date beside the withdrawal record, and follow up if that date passes. Leave the reimbursement out of your available balance until it clears. Then record it as money returned to the fund before calculating what you still need to replace through contributions. Set that replenishment amount after allowing for essentials. If you reversed an automatic transfer twice to buy groceries, lower the amount or move its date; a transfer that repeatedly comes back is not reliable saving. Recalculate your target with any changed rent or insurance deductible.
Finish by leaving a short instruction for your future self: “For an urgent repair, pay from this account, record the amount, and adjust the next savings transfer after checking upcoming bills.” Add the current balance, the next plausible surprise, and one contribution you can leave untouched through payday. Date the note so you can tell whether it reflects your latest bills. Keep it somewhere you can find without exposing account passwords, alongside your written goal so you can pick up from it next month.
Watch the explanation
How to Build a Rainy Day Fund for Real Surprises
Read the transcript
Build a rainy day fund that can cover an urgent bill today and help carry essential costs through an income gap. A useful rainy day fund starts with a plausible surprise, then grows toward essential expenses during lost income. This video shows how to set reachable targets, keep the cash accessible, automate replenishment, and review the plan as life changes. Look back over the last year or two. Find the largest unplanned bill that would have forced you to borrow. Use it as your first target, or begin with a smaller milestone you can reach. Protect rent and other essentials by lowering the transfer when necessary and extending the timeline. Once one likely bill is covered, plan for an income gap. Add housing, utilities, groceries, transportation, insurance, minimum debt payments, and obligations you cannot pause. Use actual bills to estimate one month of essential spending. Then decide how many months fit your income stability, household needs, and available support. Emergency cash should be reachable without selling an investment at an unfavorable price. Before opening an account, test how quickly money can reach the account that pays an urgent bill. Check the transfer timetable, minimum balance, fees, insurance, and available balance. Keep the first cash layer immediately accessible. Consider a CD or Treasury bill only after that buffer exists and the money can remain untouched until a suitable maturity. Check penalties, transfer steps, and sale-price risk. Also confirm whether a money market product is a deposit account or a mutual fund. Schedule a transfer shortly after payday when your balance can support it. With irregular income, move a manageable share of each payment. After the fund pays for an emergency, restart contributions at an amount that still leaves room for essentials. Review the target when rent, household size, deductibles, or income changes. Decide what the fund covers before a bill arrives. A sudden medical bill, an essential appliance failure, or income lost after a job loss could qualify. Put annual premiums, holiday spending, and known registration renewals in separate savings buckets when possible. This protects the emergency cash from predictable costs. Once a month, ask two questions. Could you pay a plausible urgent bill today, and how long could you cover essentials if income stopped? Review why the balance moved and adjust transfers that repeatedly get reversed. Send a small test transfer, note when it becomes available, and check fees and limits. The plan works when cash arrives in time and can be refilled afterward. Start with one plausible surprise, then add a layer for essential spending during lost income. Keep the first layer easy to reach, automate a manageable contribution, separate expected bills, and test the account each month. Update the targets when household costs or income stability change. Read the full article for the planners, calculators, account guidance, and detailed examples. The link is in the description.
Explore your next move
What should your next savings move be?
Which situation sounds most like yours right now?
Choose the situation closest to yours to see a practical next step.
Take this with you
Take the rainy-day fund worksheet
A one-page printable plan for your first target, essential costs, savings pace, and next check-in.
Open the download →Your take